Reading the chart
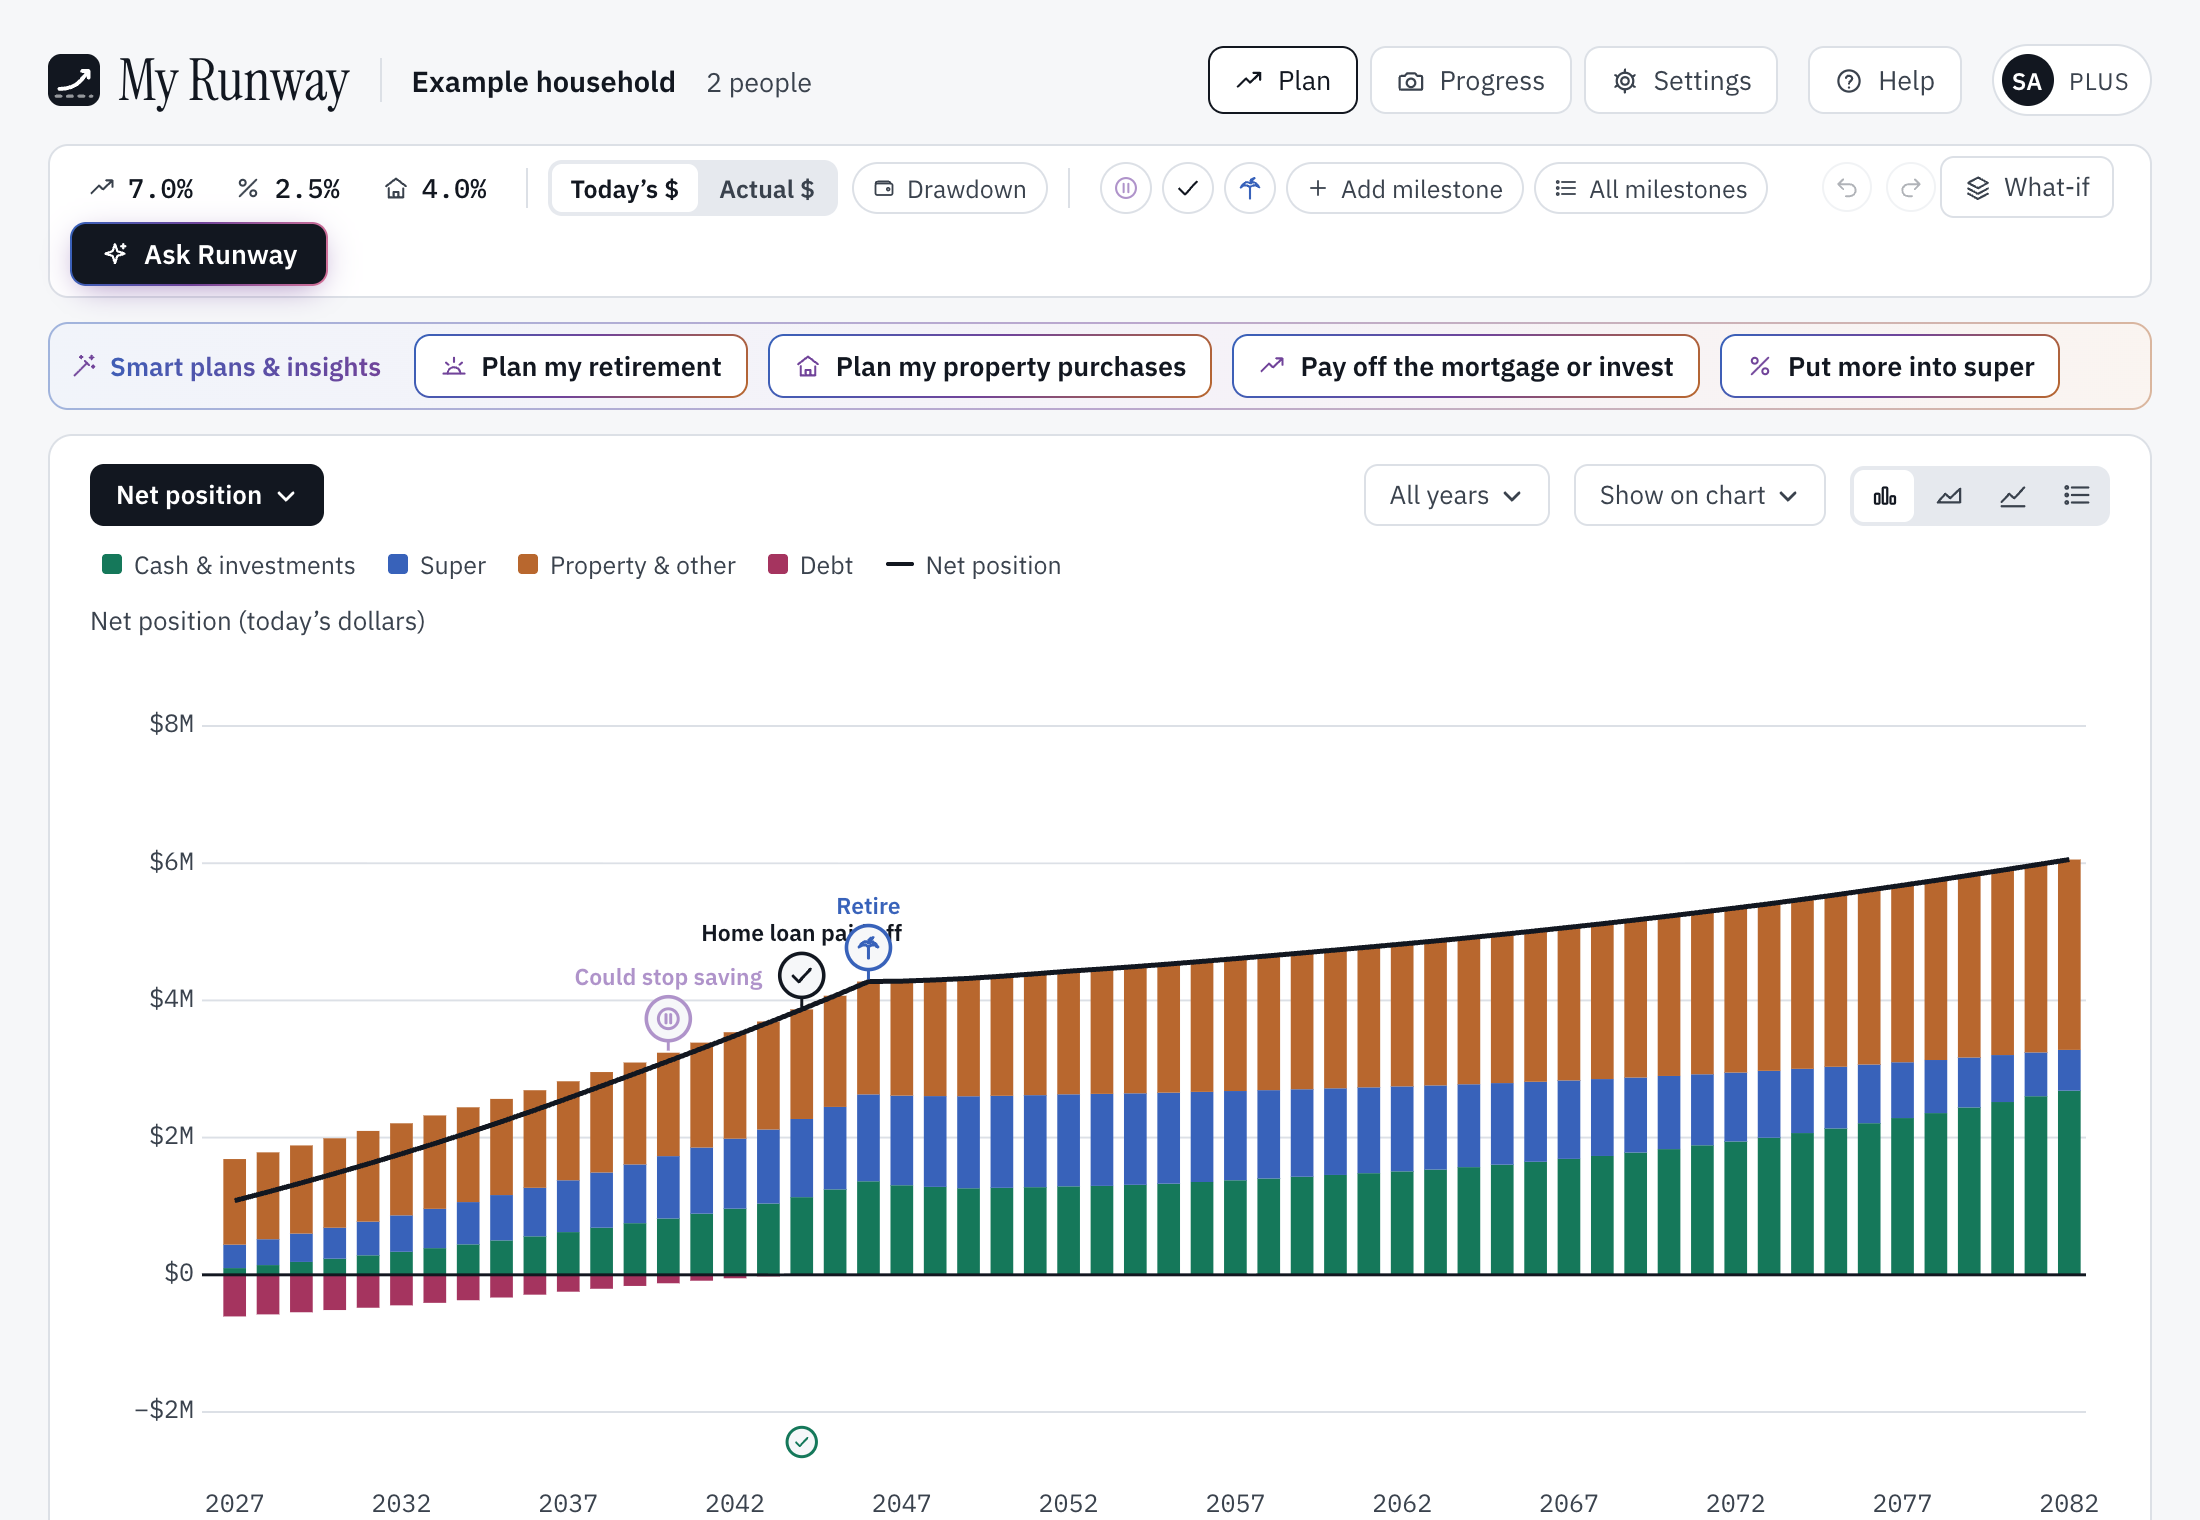
The chart shows one bar for each financial year, from this one to the end of the plan. A year reads as the financial year it is, such as 2026–27, when you point at it, in the table, in the year you open and in a what-if’s sentence; the axis beneath the bars, the CSV and the PDF show the year each ends in, 2027. Net position is what you own less what you owe.
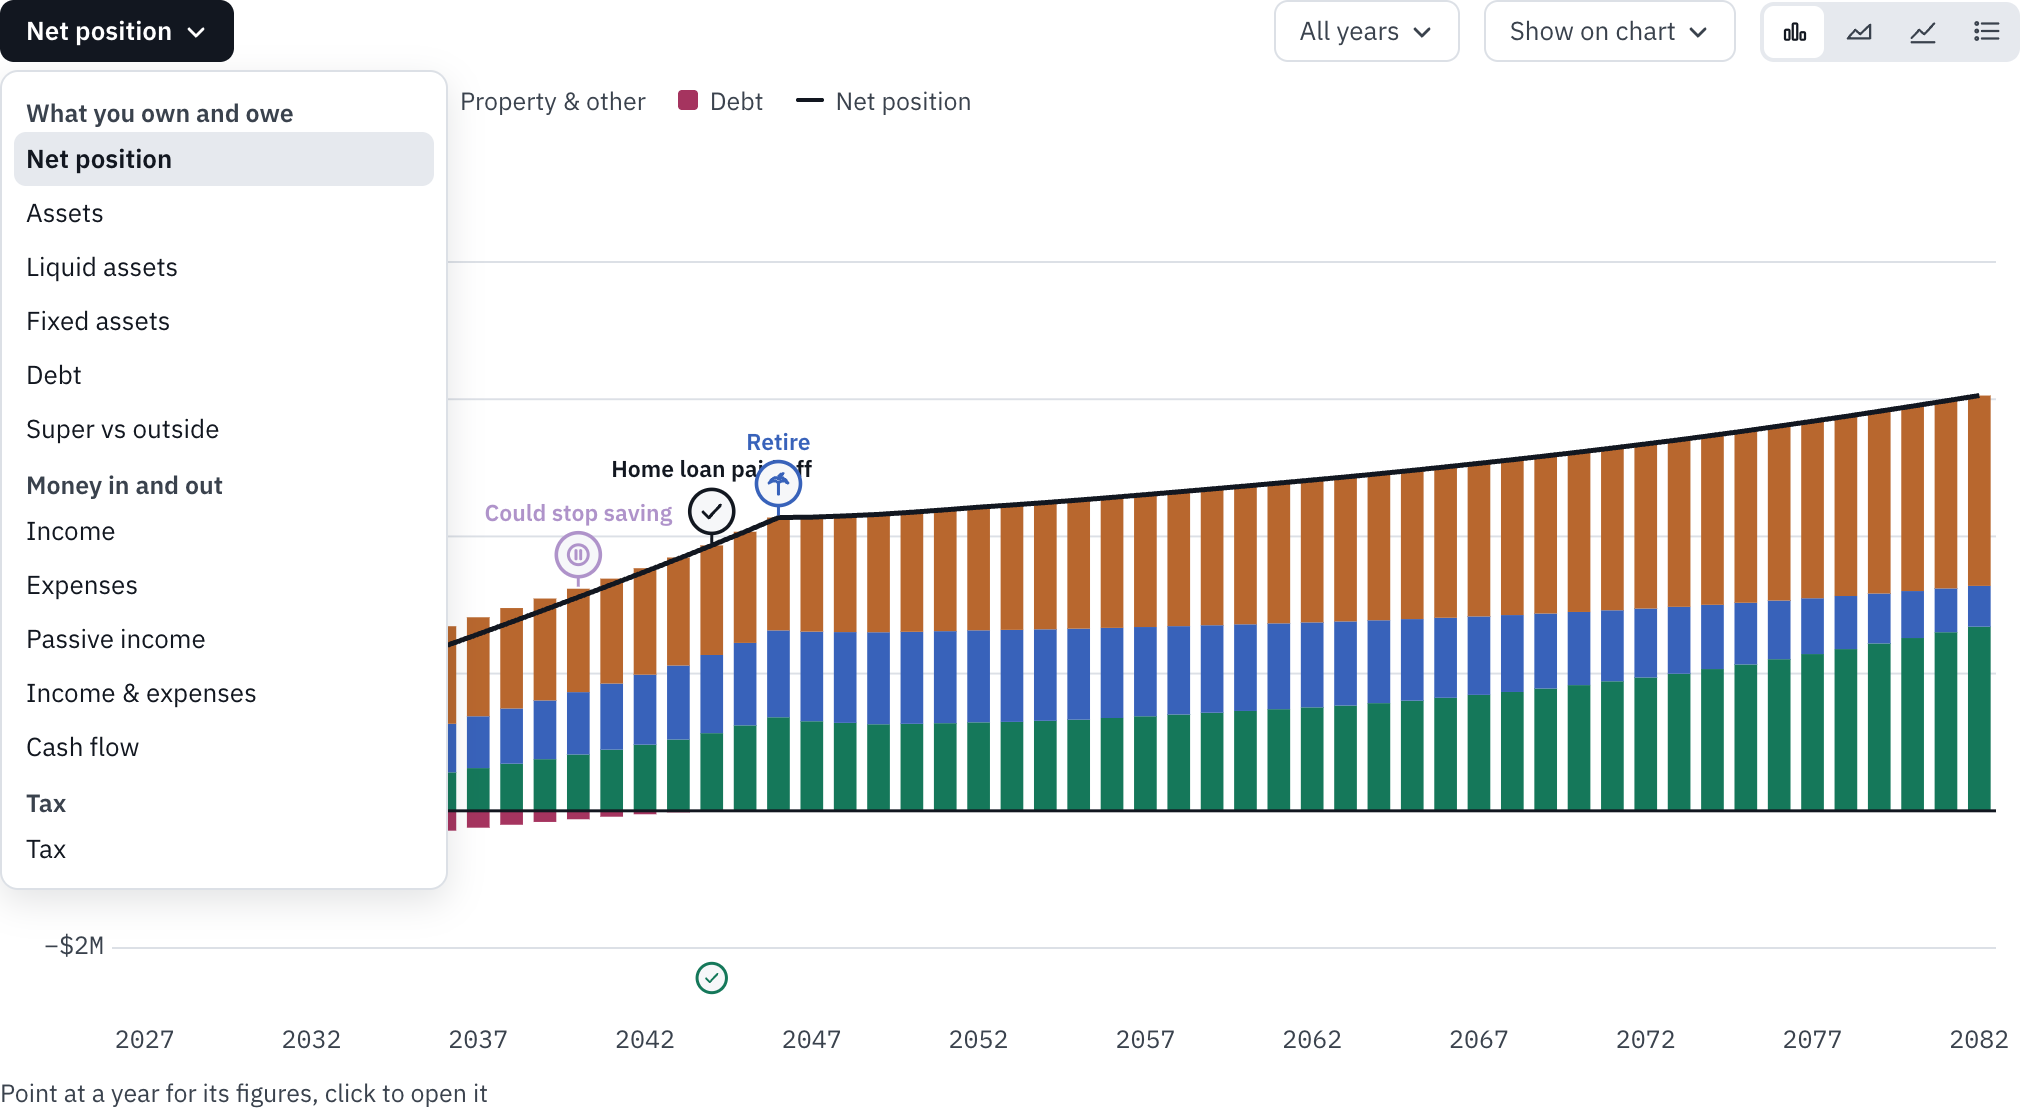
The menu above the chart, named for the view you’re on, holds the other views of the same projection, in three groups. What you own and owe: Assets, Liquid assets and Fixed assets (each account or property on its own band), Debt (each loan) and Super vs outside. Money in and out: Income (each source, and, lighter, what is drawn from each account to live on), Expenses (each expense, with tax, property costs, loan repayments and purchases), Passive income (what each investment pays, less its property costs and loan interest), Income & expenses and Cash flow. Tax: Tax, by kind, with the effective rate as a line. When there are many bands, the smallest share one, such as “Other accounts”.
On Passive income, Each property (among the chart’s tools, for a plan with a rented property) draws each rented property as one band: its rent, less its running costs and the interest the plan counts as deductible on the loans that bought it, including an equity split drawn to buy it. Above the axis it pays its way; below, it costs you, and the tooltip and the table say which. Costs no property owns, such as a share loan’s interest, keep their own band, so the bands still add to passive income after interest. It is cash before tax: depreciation is left out, though for tax a property’s loss (negative gearing) counts it, and an opened year’s tax workings list each property’s rent, costs and depreciation, and each loan’s interest. While a property bought to rent earns nothing yet, such as a build, its band is the interest on its loan alone. Each property is off when the page loads.
Draw it as Bars, Stacked area or Lines, or as a Table of the same figures. Click an entry in the key to hide or show it; with only a rate or ratio left (the Tax view’s effective rate, a Debt view ratio), it fills the chart and the dollar axis goes. On the free plan, Net position is open; the other views and the table show a padlock and a preview.
The Debt view’s key also holds up to three lines, each there when it has a figure to show and switched off to start. Owing less offsets is what you owe less what sits in each loan’s offset account, never below nothing for a loan. Portfolio LVR is the loans secured on your properties as a share of what those properties are worth; a loan secured on nothing is left out, and a property being built counts at what has been paid so far. Debt to income is what you owe at the end of each year against that year’s income before tax, such as 3.5×; a loan repaid by a sale during the year is no longer in it. The “debts × income” beside an income’s amount reads what you owe today, so the first year can differ. One of the two ratios shows at a time, on the right-hand axis. They are figures, not limits: a lender sets its own.
Point at a year for its figures and everyone’s age then. Milestones sit above the bars; purchases, sales and debts paid off sit in a row of small icons beneath them. Show on chart (an eye, on a phone) turns each kind on or off, and ages under each year too.
Some years, and the figures on the chart
All years (a calendar, on a phone), beside Show on chart, crops the chart to a From and a To year, with its table; Whole plan goes back. A cropped chart says so beneath its axis, such as “Years 2030–2045 of the plan’s 2027–2082”, so a screenshot carries it. It changes no figure and not how long the plan runs. Anything about the whole plan still reads all of it: if the money runs out after the To year, the card above the chart still says so, and the milestones above it still show the year each is reached.
Values, under Show on chart, prints the view’s headline figure on the chart, short as the axis reads, such as $1.01M: over each bar, below it when the figure is negative, or on the headline’s line, with a dot each year on every line. Where the years are narrow the figures thin out, to every second or fifth year, and one that would cover a milestone sits above it; the table has every figure. The years and Values are for this visit and start over when the page reloads, while the rest of Show on chart is kept. The CSV and PDF exports are always the whole plan.
Open a year
Click a bar to open that year: its closing net position and how it changed, what happened, its assets and debts (opening, change and closing), and its income and expenses down to the surplus or shortfall, with where it went or what covered it. A part with a change that year opens by itself and says why. Click a row to open its card. Anything you add while a year is open starts in that year. On a phone, the arrows either side of the year step to the year before or after. All years goes back.
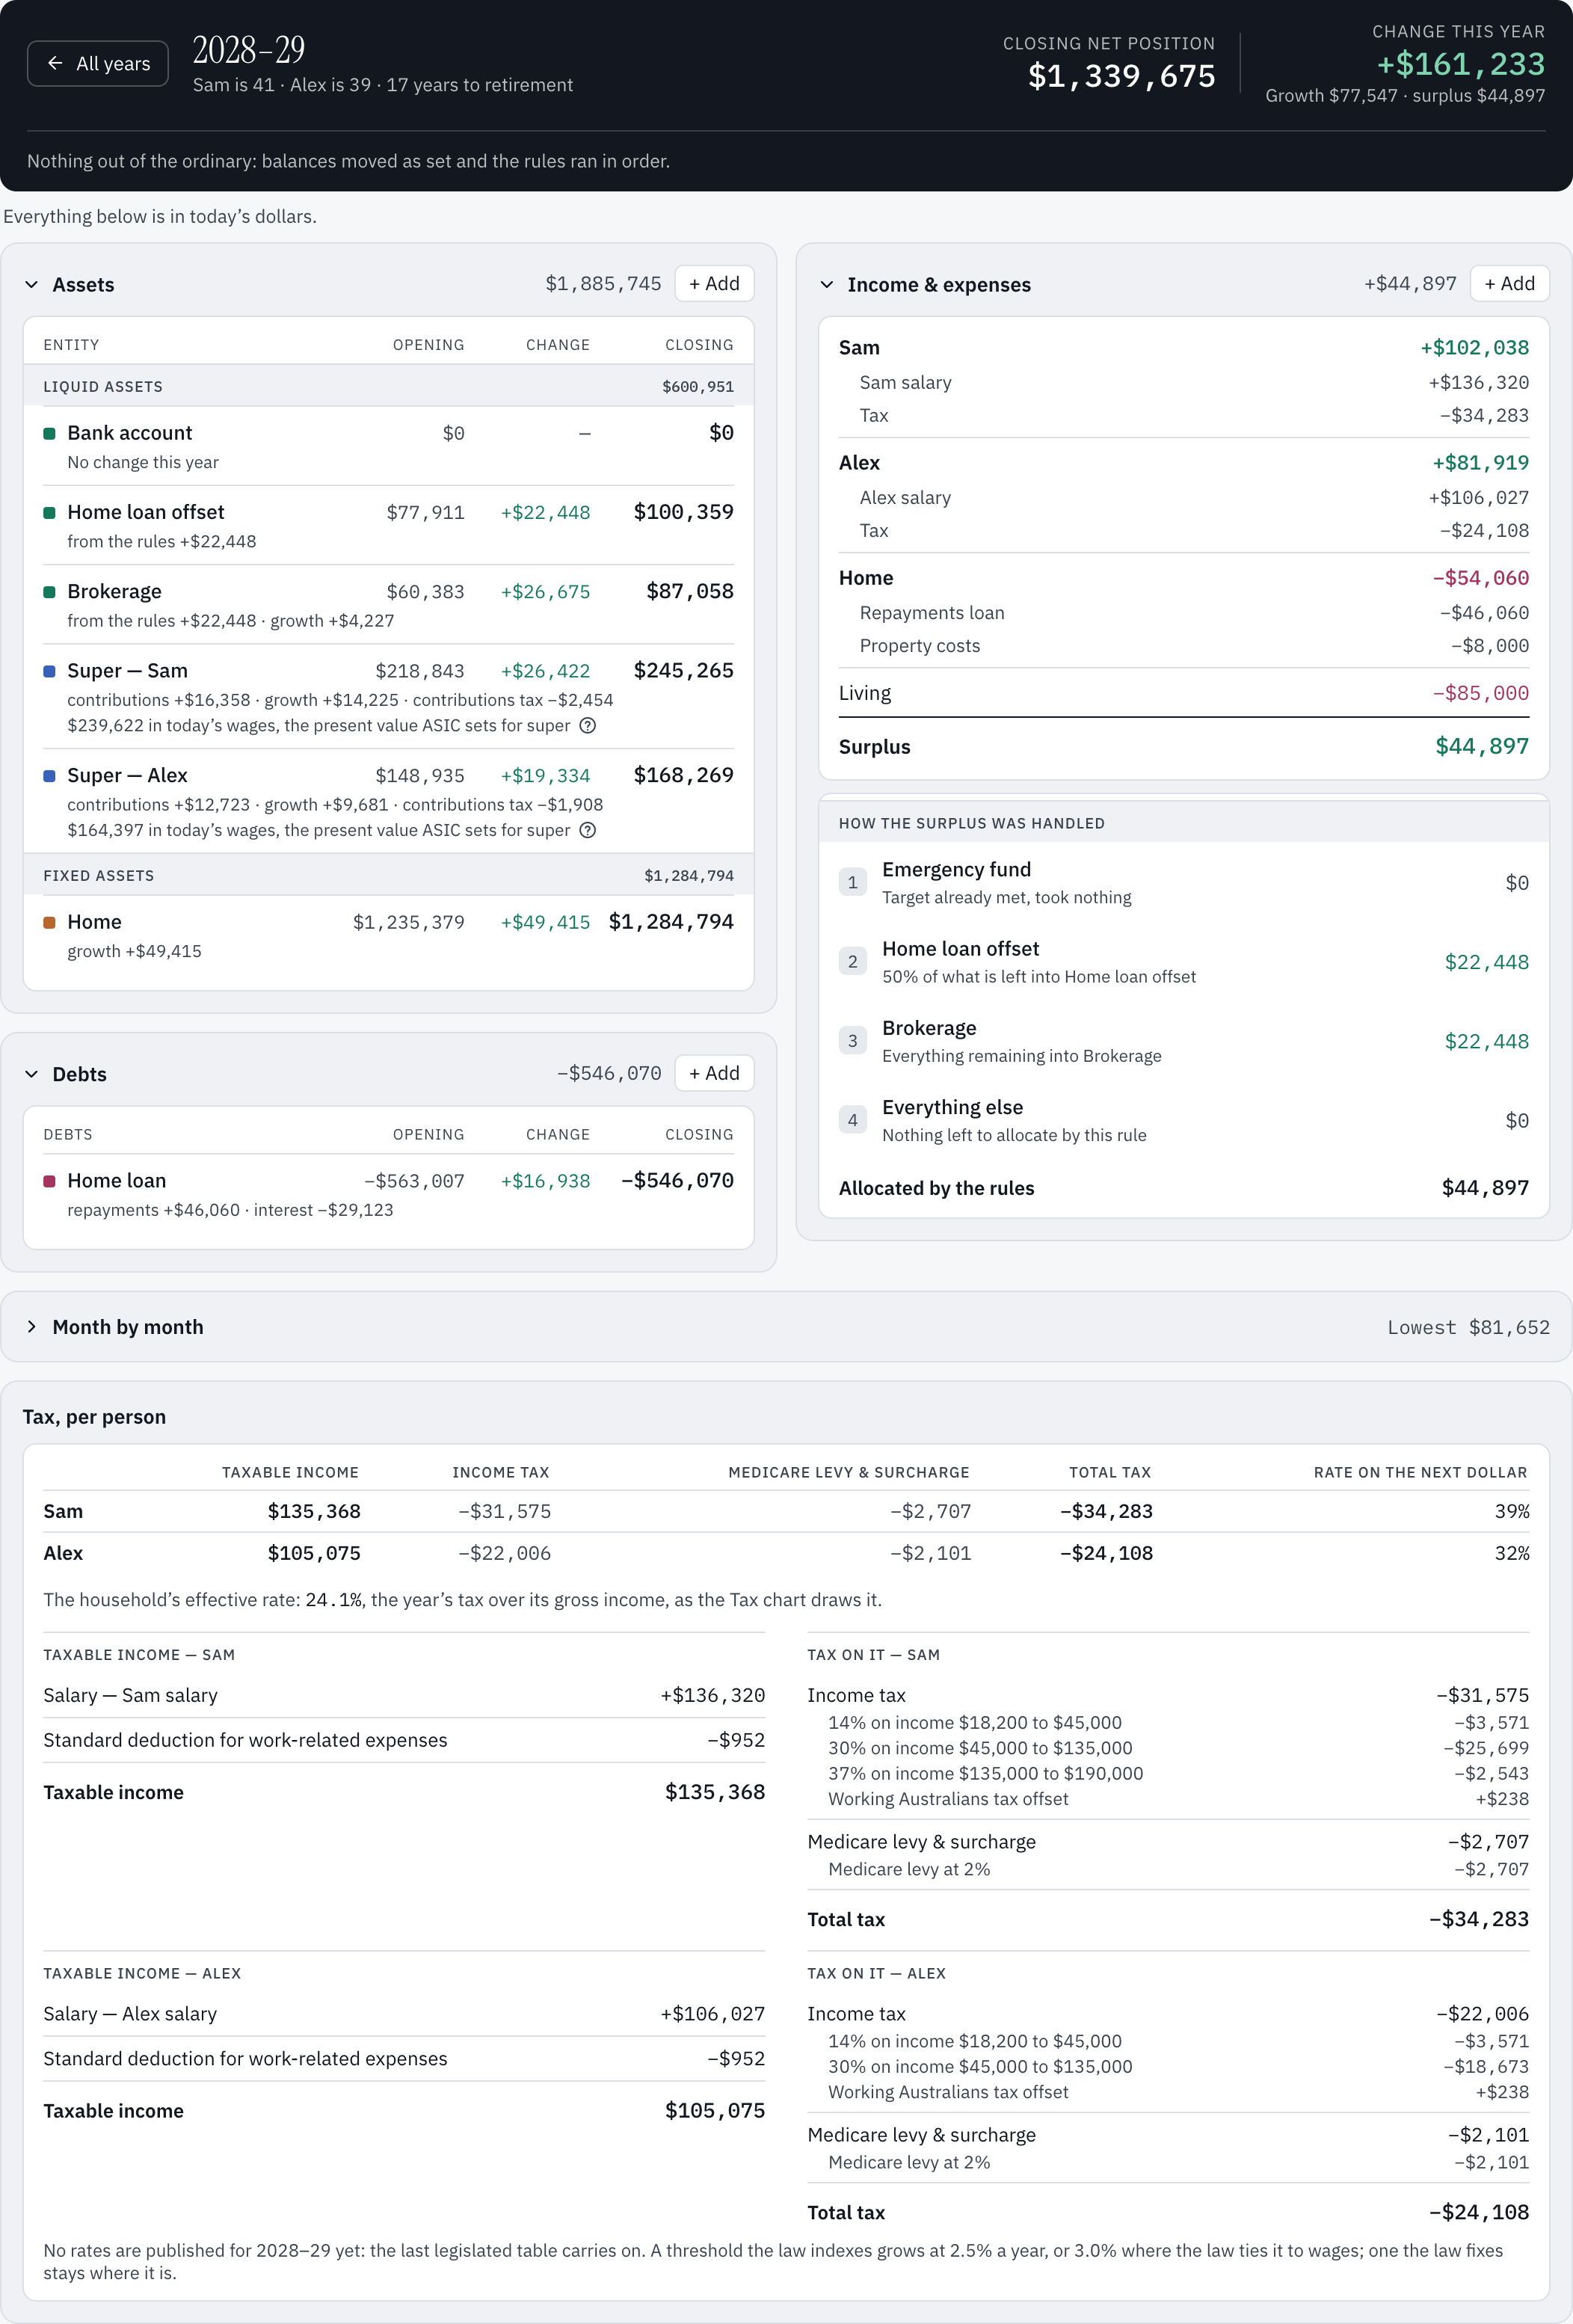
On the free plan, a year shows the totals: money in, tax, living costs, and one line for where the surplus went. Advanced insights (Plus) lists every line, how each rule took its share, and each person’s tax workings, with the rate on their next dollar (income tax, the levies, any study loan repayment and, on a high income, Division 293) and the household’s effective rate for the year.
With the keyboard: the arrow keys move between years, Home and End go to the first and last, Page Up and Page Down move ten years, Enter opens one, Escape closes it, and, on Plus, T switches to the table.
Today’s dollars
Figures are in today’s dollars unless you switch them, so an amount in 2045 reads as what it would buy now. The switch above the chart is Today’s $ and Actual $, the dollars of each year. A card for something that starts later shows its figure in the same dollars, whichever ones you typed it in; its editor says which, such as “Borrowed, in 2040 dollars”.
Super also shows a second figure, in today’s wages: the measure ASIC sets for super calculators. Until the person retires (their Retire milestone, or 67 without one, and never before their preservation age) it divides by wage rises, 3.7% a year unless you change it, and after it by inflation. Wages rise faster than prices, so it reads lower than today’s dollars. You see it when you open a super account (its balance at retirement), beside its balance in a year you open, in Put more into super, and under Plan my retirement’s answer (the spending a year, paid partly from super), each with a ? that explains it. It comes from the same projection and changes nothing else.
When the money runs out
A year the plan can’t pay for is washed red on the chart, and a card above it says The money runs out in that year: your age then, the Years short and how much is short in all. Its buttons open that year, the Drawdown order, or Try a what-if (Plus). The card can’t be dismissed; it goes once the plan pays its way.
Months below zero
A small red dot at the foot of a year means your cash runs below zero in at least one month of it, even if the year pays its way by June: a purchase paid in July, say, before the year’s pay has built up. Open the year and a line under its header says how many months and how low. Month by month (Plus), open on such a year, shows your cash and offset accounts at the end of each month, red below zero, and a month opens to what came in and went out. Pay arrives with tax taken out, and the rest of a year’s tax comes back as a refund, or goes out as a bill, in October of the next year (or the month set in Plan settings). Months already passed are greyed. A recurring income or expense arrives a twelfth a month, unless an editor’s Paid says Once a year or Quarterly.
The rates above the chart
The investment return, inflation and property growth sit above the chart as a percentage each; point at one for its name. Click one to change it for the whole plan with the − and + or the slider, and the chart moves as you drag. On a phone the three sit together behind Rates. Anything that has set its own rate keeps it. The rest of the rates are in Settings, under Rates.
Still stuck?
Signed in? Choose Help at the top of the app, pick what it’s about and tell us what happened; it reaches us with the page you were on, and you get a copy. Otherwise write to info@myrunway.com.au. We reply by email. Please don’t send passwords or account numbers.